

Acorns Early: Kids Money App
4.5

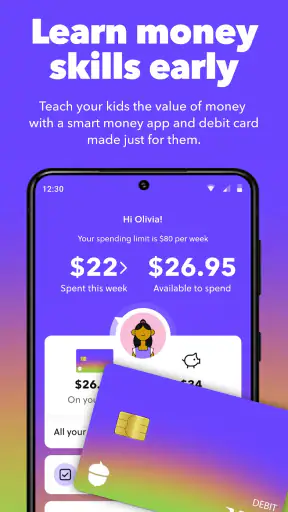
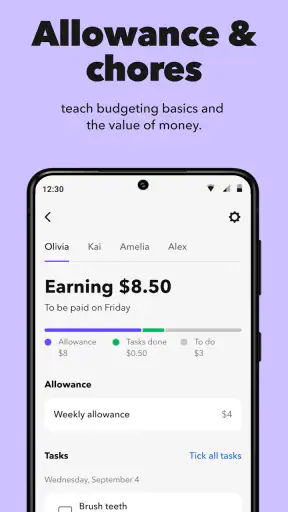
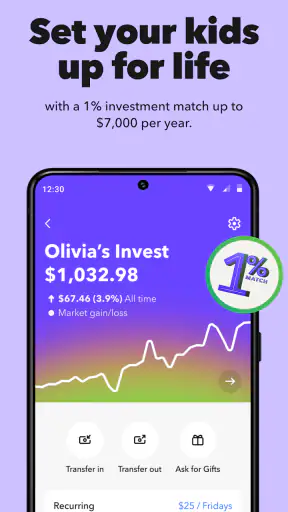
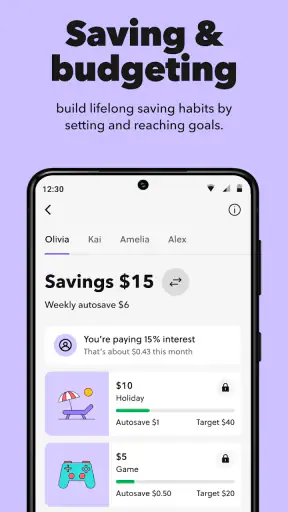
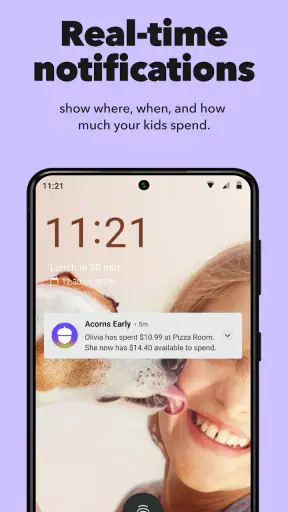
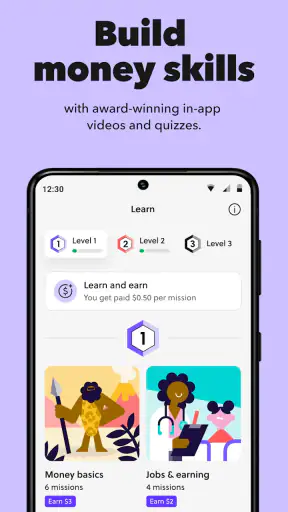
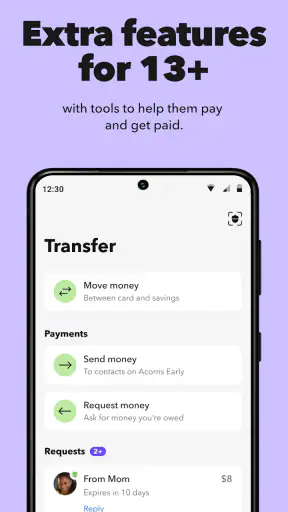
Acorns Early: Kids Money App is a finance app from Acorns aimed at families who want to introduce children and teenagers to investing in a structured way. I approached it less like a general budgeting tool and more like a parent-and-child financial planning companion. That distinction matters: the app is not simply a digital piggy bank, and it is not a replacement for a full brokerage platform designed for experienced adult investors.
After spending time with the app, my overall impression is that its value depends heavily on how clearly a family defines its goal before getting started. If the aim is to create a long-term investing habit for a child, the concept is appealing. If the expectation is instant access to spending money, detailed trading controls, or a complete lesson-based money course, the experience may feel narrower than expected.
The app is free to install, carries an Everyone age rating, and is listed under Finance. It was released on November 8, 2024, and the current version is 9.7.0. It requires Android 7.0 or later. Its average rating is 4.5 from around 3.2 thousand ratings, with more than 100 thousand installs, so it has already attracted meaningful interest without feeling like an obscure experiment.
Where families tend to get stuck
The first point of friction is understanding who the app is really for. The child or teenager is the focus of the financial plan, but the adult is usually the person responsible for making decisions and completing the important account steps. That can create confusion if a young user expects to open the app and manage everything independently.
I recommend treating the first session as a parent-led setup rather than handing the phone to a child and expecting the purpose to be obvious. Before opening the app, decide whether you are trying to build a long-term investment habit, organize money for a future goal, or simply teach basic financial responsibility. Those goals overlap, but they do not produce the same expectations.
Another common stumbling block is the word “investing.” A child may interpret it as something active and fast-moving, while a parent may be thinking about gradual, long-term growth. This difference should be discussed before using the app. The interface can support a family conversation, but it cannot replace one. I found that the experience makes more sense when the adult explains that an investing plan is not the same as a spending balance.
The most useful early decision is agreeing on the purpose of the money before entering any details. A specific purpose gives the app context and helps prevent a child from judging the experience by the wrong standard. A long-term plan should not be evaluated like a checking account, and a learning exercise should not be judged like a professional investment dashboard.
Families can also get stuck when they expect every part of the child’s financial life to appear in one place. This app’s identity is centered on an investing plan for kids and teens. That makes it potentially useful for one part of a broader money routine, but it does not automatically replace conversations about allowances, saving jars, spending limits, or household budgeting.
What to clarify before creating a plan
I would write down three simple answers first: who will supervise the plan, what the money is intended for, and how often the family will review progress. This small preparation step prevents a surprisingly common problem: opening an account without deciding what “success” means.
It is also worth deciding how much explanation the child needs. A younger child may benefit from a simple story about saving for a future goal. A teenager may want to know why money is invested, what risk means, and why results can change. The app can be part of that discussion, but it should not be the only source of understanding.
Parents should also be comfortable with the idea that investing involves uncertainty. I would not present the app as a guaranteed way to grow money. The most responsible use is to frame it as a practical introduction to long-term financial thinking, with the adult remaining involved in the decisions and expectations.
Setup checks that prevent avoidable problems
Before blaming the app for a failed or confusing setup, I would start with the basics. Confirm that the device meets the Android requirement, update the app if an update is available, and make sure the phone has a stable internet connection. These checks sound ordinary, but finance apps are especially frustrating when a connection drops during a sensitive step.
Because the product involves a child or teenager and an adult-led financial plan, read each screen carefully instead of tapping through quickly. A rushed setup makes it harder to remember which information belongs to the adult, which information concerns the child, and what the selected plan is supposed to accomplish.
I also suggest using a quiet moment rather than trying to complete setup while commuting, supervising homework, or switching between several devices. If a screen requires thought, stop there and make a note of what you need to decide. Repeatedly backing out and restarting can make the process feel more complicated than it really is.
Keep the app and the device’s operating system in a normal, supported state. If the phone is heavily modified, running aggressive battery-saving software, or blocking background activity, troubleshooting becomes harder because the problem may be outside the app. I would first test the app under ordinary device settings before changing anything more dramatic.
One practical tip is to separate technical setup from the family conversation. First make sure the app opens and the adult can move through the relevant screens. Then explain the plan to the child in age-appropriate language. Trying to solve a login issue while also explaining investing tends to create unnecessary pressure for everyone.
When a screen appears stuck
If a page does not load, I would wait briefly, check the connection, and try again once rather than repeatedly tapping the same control. Force-closing and reopening the app is a reasonable next step. If the problem continues, restart the device and test again on a reliable network.
Do not immediately clear all app data or reinstall if you are unsure how the current session is being handled. In a finance app, preserving access information and keeping track of what has already been completed is more important than applying every generic troubleshooting trick. Make a note of the exact screen and message first.
If the app opens normally but one particular action fails, that detail is useful. A complete launch failure points toward the device, installation, or connection. A single blocked step may instead relate to the information entered, the account state, or a service-side issue. Describing the difference clearly will make any support conversation more productive.
Recovering a workflow without starting over
When a family loses track of where it stopped, I recommend reconstructing the workflow calmly. First identify the last screen that definitely completed. Then reopen the app and check whether the next step is still pending. Avoid assuming that a screen disappearing means the whole process failed.
This is particularly important when an adult is setting up a plan for a child. The adult may think the child’s portion has been created, while the app may still be waiting for an earlier step. Rather than entering information again, compare the current screen with your notes and look for a clear indication of what remains.
A useful recovery habit is to keep a short private checklist during setup: app installed, adult access working, child or teen details reviewed, plan purpose understood, and any remaining action identified. This is not a feature of the app; it is a simple way to reduce confusion when setup is interrupted.
If the app closes unexpectedly, reopen it before repeating anything. If the same step keeps failing, capture the wording of the error without sharing sensitive financial or personal information publicly. Screenshots can help when contacting support, but they should be reviewed carefully so private details are not exposed.
Families should also distinguish between a forgotten password, an unavailable verification message, and a page that simply will not load. These problems need different responses. Checking the correct email or phone inbox, confirming that the device can receive messages, and avoiding repeated attempts in a short period are sensible general steps.
Keeping the child’s experience understandable
Recovery is not only technical. If a teenager sees an incomplete plan or a delayed screen, they may assume that investing is unreliable or that they did something wrong. I would explain that financial apps sometimes require adult review and that a pause does not necessarily mean the plan has disappeared.
For younger children, it may be better to continue the conversation away from the phone and return later. The app should support a healthy money habit, not turn a minor technical problem into a stressful family event. A calm explanation is more educational than rushing through the process.
Once the plan is active, establish a review routine that matches the child’s age and attention span. Checking constantly can encourage an unhealthy focus on short-term changes. A planned conversation about goals and choices is more useful than repeatedly refreshing the screen.
When the app is not the cause
Not every confusing result comes from a software fault. A family may expect an immediate visible change after completing a step, while the underlying financial process requires time. The app can display a plan, but it cannot make investing behave like an instant transfer or a video game reward.
Device conditions are another frequent source of trouble. Limited storage, an outdated operating system, unstable Wi-Fi, restricted notifications, or battery management can interfere with normal use. If the same account behaves differently on another suitable device or network, that comparison can reveal whether the original phone is involved.
Account information also deserves careful attention. A mismatch in names, contact details, or other required information can stop progress even when the app itself is functioning normally. The safest response is to review entries slowly and use the app’s own guidance, rather than guessing or entering approximate information just to move forward.
It is also important not to confuse a financial decision with a technical error. If a parent dislikes the available level of control, wants more investment choices, or expects detailed trading tools, that may be a product-fit issue rather than a malfunction. Acorns Early is designed around a child- and teen-focused investing plan, so someone seeking advanced adult investing controls may be better served by a conventional brokerage app.
The same applies to families looking mainly for spending management. If the priority is tracking every purchase, managing a debit card, or assigning detailed chores and allowances, a dedicated family budgeting or money-management service may be a better match. This app can sit beside those tools, but I would not assume it replaces them.
Who benefits most from this approach
I think the strongest audience is a parent who wants a simple starting point for discussing investing with a child or teenager. The app gives that conversation a practical object: a plan connected to the young person’s financial future. It may also suit families who prefer an adult-supervised approach rather than giving a young user unrestricted control.
A realistic example would be a parent and teenager setting aside time on a weekend to discuss a future goal. The parent handles the account responsibilities, explains why the plan is long term, and agrees to review it at a sensible interval. The teenager then has a concrete way to connect saving, patience, and future planning instead of hearing those ideas only as abstract advice.
The app is less suitable for someone who wants to trade actively, compare a wide range of securities, or make rapid investment decisions. It is also not ideal for a family that does not want an adult involved in the financial process. In those situations, the product’s focus becomes a limitation rather than a strength.
Another trade-off is that simplicity can leave experienced users wanting more detail. A parent who already understands portfolios, taxes, risk allocation, and account structures may find a child-focused workflow too guided. That is not necessarily a flaw, but it means the app should be judged by its educational and family-planning role, not by the standards of an advanced investment terminal.
My practical verdict after using Acorns Early
Acorns Early works best when a family wants to make investing part of a supervised financial conversation. I like that its purpose is clear: it is built around financial wellness for kids and teens rather than trying to be everything from a bank account to a professional trading workstation.
The strongest advice I can give is to prepare before setup, keep the adult role clear, and treat troubleshooting as a process rather than a reason to restart everything. Check the device and connection first, record the screen where progress stops, and avoid repeating sensitive steps without knowing whether they already completed.
Its free availability and Everyone rating make it approachable, while the current version and Android compatibility make it accessible to many older devices. Still, accessibility should not be confused with simplicity in every situation. Financial setup deserves attention, and families should be ready to explain investing honestly rather than presenting it as guaranteed growth.
My recommendation is positive for parents who want a guided starting point for a child’s or teenager’s long-term investing plan and who are willing to stay involved. I would choose a different kind of finance app for detailed household budgeting, everyday spending controls, or advanced personal investing. Used for the purpose it appears designed to serve, however, Acorns Early can turn an otherwise vague money lesson into a more concrete family routine.
4.5
534.00 Reviews
Pros
- Teaches saving through simple
- age-appropriate activities.
- Parents can set up recurring investments for a child.
- Interactive lessons make money concepts easier to understand.
- Helps children connect chores with earning and saving goals.
- Family-focused design keeps money learning approachable and engaging.
Cons
- Requires a parent-managed Acorns account to access its full value.
- Investment features may vary depending on the parent’s Acorns plan.
- Some children may outgrow the basic lessons quickly.
- Parents must supervise financial discussions and account activity.
- Availability and features can differ by location or account type.


